
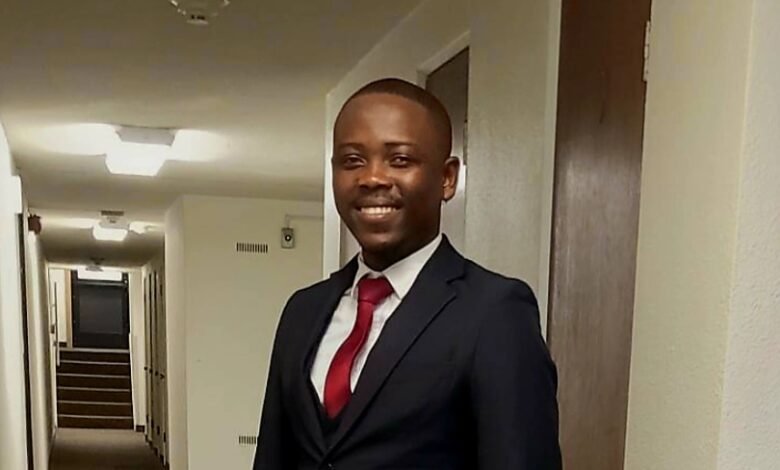
Anthony Kwesi Ashun, a Doctor of Business Administration (DBA) student specialising in Business Intelligence and Data Analytics, is advocating for greater use of data and financial intelligence to address Ghana’s persistent Small and Medium-sized Enterprise (SME) financing challenges.
With seven years of professional experience at the Ghana Statistical Service, Anthony has contributed to several major national data collection and research initiatives, including the Annual Household Income and Expenditure Survey (AHIES), Integrated Business Enterprise Survey (IBES), Agribusiness Tracker Survey, and the 2021 Population and Housing Census.
His professional experience, including work supported by institutions such as the World Bank, Bank of Ghana, BMZ and HISWAP, has strengthened his conviction that reliable, timely and well-analysed data are essential for sound financial and economic decision-making.
Kwesi Ashun believes data-driven approaches can help improve SME creditworthiness, financing readiness, financial resilience, risk assessment and access to appropriate sources of capital.
Improving SME Financing Through Data
According to Anthony, Ghana’s SME financing challenges should not be viewed solely as a matter of increasing the amount of money available to businesses.
“Access to finance is not simply about making more money available. Financial institutions also need reliable information to assess businesses, while SMEs need better financial information to demonstrate their capacity and understand their financing needs,” he explained.
Available evidence highlights the scale of the challenge. The World Bank’s 2023 Enterprise Survey found that 43.3 percent of surveyed establishments identified access to finance as their biggest business obstacle, while 77.3 percent reported having no loan or line of credit from a financial institution.
Meanwhile, Bank of Ghana data indicate that outstanding private-sector credit reached GH¢89.12 billion in 2024, although real credit growth stood at only 2.0 percent. The banking sector’s non-performing loan ratio also increased from 20.58 percent in 2023 to 21.79 percent in 2024.
Anthony Kwesi Ashun said the figures suggest that Ghana’s SME financing challenge goes beyond the simple availability of capital. Issues such as credit risk, financing costs, information asymmetry and the ability of businesses to demonstrate financial strength also play significant roles.
He therefore recommended the development of data-driven SME creditworthiness assessment frameworks that complement traditional lending methods.
Such frameworks, he said, could incorporate verifiable indicators including revenue patterns, cash flows, transaction activity, receivables, inventory levels, business performance and sector-specific characteristics.
“The goal is not to eliminate risk. The goal is to use better information to understand risk more accurately,” Anthony said.
Strengthening SME Financial Resilience
Mr Ashun also recommended the introduction of SME financing-readiness assessments to help businesses evaluate their financial position before approaching lenders.
Such assessments could examine financial records, cash-flow patterns, existing debt obligations, revenue stability and working-capital requirements.
He said cash-flow forecasting, financial-health monitoring and early-warning indicators could also enable SMEs to identify potential financial difficulties before they become severe.
Indicators such as declining revenues, rising debt levels, deteriorating liquidity and growing receivables, he noted, could provide early signals requiring management intervention.
“An SME can receive financing and still experience financial distress if the financing does not match its cash-flow cycle or if the business lacks the systems to manage it effectively,” he explained.
Using Data to Inform SME Financing Policy
Anthony Kwesi Ashun believes Ghana can make better use of its existing economic and socioeconomic datasets to generate actionable financial intelligence for SMEs, financial institutions and policymakers.
He said data-driven research could help identify SMEs that are most vulnerable to financial shocks, sectors facing greater financing constraints, regional variations in financing needs and business characteristics associated with stronger financial resilience.
He further called for stronger collaboration among statistical institutions, financial institutions, policymakers, development organisations and SMEs to ensure that economic data are translated into practical financing solutions.
“Data become more valuable when they can be translated into decisions and practical interventions,” he added.
Building a More Data-Driven SME Financing Ecosystem
Looking ahead, Anthony identified financing-readiness assessments, data-driven credit-risk analysis, cash-flow forecasting, financial-health monitoring, sector-specific risk models and policy-oriented research as important tools for improving Ghana’s SME financing environment.
“My interest is in bridging the gap between data and financial decision-making. If SMEs have better information about their own financial health, and financial institutions have better information with which to evaluate businesses, we can create the conditions for more informed and responsible financing decisions,” he said.
Anthony Kwesi Ashun believes that making better use of Ghana’s business and socioeconomic data can contribute to a more transparent, resilient and inclusive SME financing ecosystem.
Such an approach, he said, could help viable businesses demonstrate their financial capacity, access appropriate capital, manage risks more effectively and ultimately contribute to sustainable economic growth and employment creation.